

Consultancy-led mortgage advice
Complicated case? Talk to a specialist who reads the whole story.
Complex income, an unusual property, a credit problem or a CCJ doesn’t have to be the end of the road. Andy works out where your case really stands before anything goes near a lender.
First consultation free
No credit search
Whole of the UK
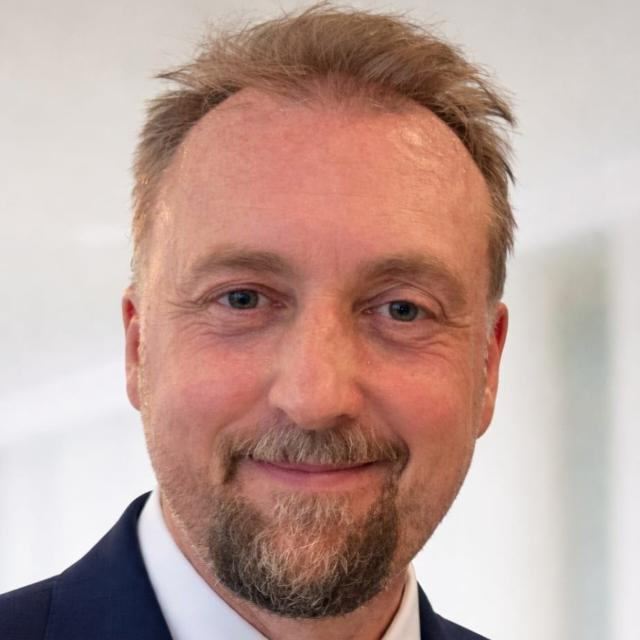
Andy Craddock
Founder & adviser · 20+ years in lending
You speak to Andy from the first call. If your case won’t work, you’ll hear it in that conversation, not six weeks later.
Where should Andy start?
A few quick questions so Andy understands your case before he calls. Takes about two minutes, with no credit search.
Confidential · no credit search · about 2 minutes
What we’ll ask
Your plans→The tricky bit→Timing→Contact→Done
This is an enquiry, not an application. Nothing goes to a lender.
The consultancy approach
Understand the case first. Apply second.
A declined mortgage isn’t always the end of it. Sometimes the case went to the wrong lender, or the reason it works was never explained. Andy starts with a consultation, not a form.
We tell you no
If a case won’t work, you hear it in the first conversation, rather than after weeks of waiting and a valuation fee. Often with what would change the answer.
The right lender, not the nearest
Specialist cases depend on criteria: how a lender treats your income, your credit history or your property. Matching that is the job.
The story, told properly
Your case is written up for the underwriter, with the reason it works stated clearly rather than left to be guessed.
The whole cost, written down
Rate, fees, valuation and legal costs set out together, because that’s the number that matters.
Specialist areas
The cases the high street finds awkward
Complex income
Self-employed, limited company directors, contractors, several jobs, foreign income, bonuses and commission.
Read about complex income →
Hard-to-place property
Non-standard construction, flats above shops, ex-local authority, short leases and other homes lenders hesitate over.
Read about unusual property →
Problems with credit
Missed payments, defaults, arrears, debt management plans, IVAs and past bankruptcy.
Read about credit problems →
CCJs
County court judgments, satisfied or not. What lenders look at, and what you can do now to help.
Read about CCJs →
How a case runs
Four steps, one adviser
1
A proper conversation
Twenty minutes or so on your income, credit history, the property and your deadline. Free, with no credit search and no obligation.
2
Search & shortlist
Terms sounded out with lenders whose criteria genuinely fit, then set out side by side with the real cost.
3
Packaged & submitted
The case is written up for the underwriter, with the documents they’ll want ready from the start.
4
Through to completion
Chased weekly, with valuers and solicitors kept moving, and a review before your deal ends.
Worth knowing
Why good cases get turned down
A “no” from one lender is not a “no” from the market. High-street lenders mostly decide by computer, against rigid rules. Specialist cases tend to fall through the gaps for three reasons:
- The income isn’t read properly. Retained profit, a day rate or a bonus is ignored or averaged down.
- The property doesn’t fit the box. One lender’s “unmortgageable” is another lender’s standard case.
- The credit file tells half a story. A default from four years ago looks the same as last month’s to a scorecard.
Before you apply anywhere else
Every full application usually leaves a hard search on your credit file, and several in a short space of time can make the next lender more cautious. Talking to Andy first costs nothing and leaves no mark.
Talk to Andy first →
Frequently asked questions
Will talking to you affect my credit score?
No. The first consultation involves no credit search at all. A lender will only search your file later, with your agreement, when you decide to apply.
Can you guarantee me a mortgage?
No one honestly can. All lending is subject to status and lender criteria. What Andy can do is tell you plainly whether your case is likely to work, which lenders it suits, and what might improve your chances.
Do you charge a fee?
The first consultation is free. If a fee applies for arranging your mortgage, it’s explained in writing before you commit to anything. [to confirm]
I’ve already been declined. Is it worth trying again?
Often, yes, but pause before you apply anywhere else. Find out why you were declined, check your credit file with Experian, Equifax and TransUnion, and talk the case through first so the next application is the right one.
Do you sell my data?
No. Your details are only used to handle your enquiry. See Privacy & data use for the plain-English version.
Tell Andy about your case
An honest view of whether it can be done, and roughly on what terms. No credit search, no obligation.
First consultation free · no credit search · whole of the UK